All Categories
Featured
Cheap Individual Medical Quotes for 2026
The leading indexed universal life (IUL) insurance coverage prepares in 2026 originated from providers like Prudential, Pacific Life and Lincoln Financial, but the very best alternative depends upon your monetary objectives, threat tolerance and policy structure. This guide compares leading IUL providers based upon flexibility, development capacity and policy functions to help you recognize the strongest choices.
Pacific Life refers to Pacific Life Insurance Coverage Business and its subsidiary Pacific Life & Annuity Business. Insurance items can be released in all states, except New york city, by Pacific Life Insurance Coverage Business and in all states by Pacific Life & Annuity Business. Product/material accessibility and features may vary by state.
Pacific Life, its affiliates, their distributors and respective representatives do not provide tax, accounting or legal guidance. Any taxpayer should consult based on the taxpayer's specific circumstances from an independent tax advisor or lawyer. Insurance coverage products and their warranties, including optional advantages and any crediting rates, are backed by the monetary strength and claims-paying capability of the issuing insurer.
The home workplace for Pacific Life Insurance coverage Company is located in Omaha, Nebraska. Pacific Life Insurance Business and Pacific Life & Annuity Business.
Updated September 2026 by, ChFC, CLU, AEP, EAThere is a lot hype and hate around Indexed Universal Life on social networks, you need to be thorough about selecting an IUL business before participating in a long-lasting contract., IUL can be an important tool to buffer versus market losses and taxes in retirement while acting as your own private banking mechanism the whole time the way., Indexed Universal Life can be costly survivor benefit defense cannibalizing your cash worth account.
Top Medicare Supplement Plans for 2026
In the sensible words of vocalist Tom Waits: Here's how you can end up being a better-educated shopper when vetting the best Indexed Universal Life business: Do strategy to max-fund your IUL for at least 4 out of the first 7-yearsDo run an illustration with lighter premiums in case you can't overfundDo run illustrations showing both 1% and 2% listed below the default development rateDo ask to have a comprehensive fee report run for each circumstance to see the impactDo make certain the releasing insurance business is a mutual insurance companyDo discover just how much of the cash worth development originates from non-guaranteed bonusesDo need a locked/capped policy loan that still takes part in the indexed accountsDo demand solid S&P 500 indexed crediting accounts, ideally with an uncapped option Do not be captivated by algorithmic volatility-controlled indexes you can't track or understandDon't depend on non-guaranteed bonuses to be there for you over the next numerous decadesDon't simply select the illustration that appears to have the most cash value in retirementDon't pick your IUL company just by who has the highest IUL cap rate (today)Do not just compare IUL business based exclusively on their default highlighted ratesDon't assume you will constantly have the ability to max-fund your IUL according to planDon't limp in and light-fund an IUL unless you can max-fund it extremely soonDon't choose a stock insurance provider over a shared companyBelieve us now, and thank us later on.
Here are the four main factors we focus on when examining the very best IUL policies for money accumulation: Seeing the ratings and balance sheets of the top IUL companies in a side-by-side contrast is the primary step in strolling our clients through the IUL education process. This is an item you're preferably buying into for your whole life, so the monetary solvency and credit ratings relative to other Indexed Universal Life insurance companies will be very essential.
If you do not see the name of what appears to be the best-performing IUL company on our list below, this is probably the reason. The finest have not just one, but numerous diverse indexed accounts to grow your money worth account in various market environments. Preferably, you have not only a high cap, but an uncapped strategy.
Insurance in Bellflower CATerm vs Whole Life Insurance Advice
Nevertheless, be careful if an IUL's finest indexed accounts are volatility control indexes (VCIs). These VCIs are provided by popular investment banks with complicated algorithms to move you in and out of the market. The problem is, you frequently lose your direct exposure to stocks when you desire it the a lot of.

Latest Posts

Ensuring Financial Protection Options

Essential Medicare Selection Advice in 2026
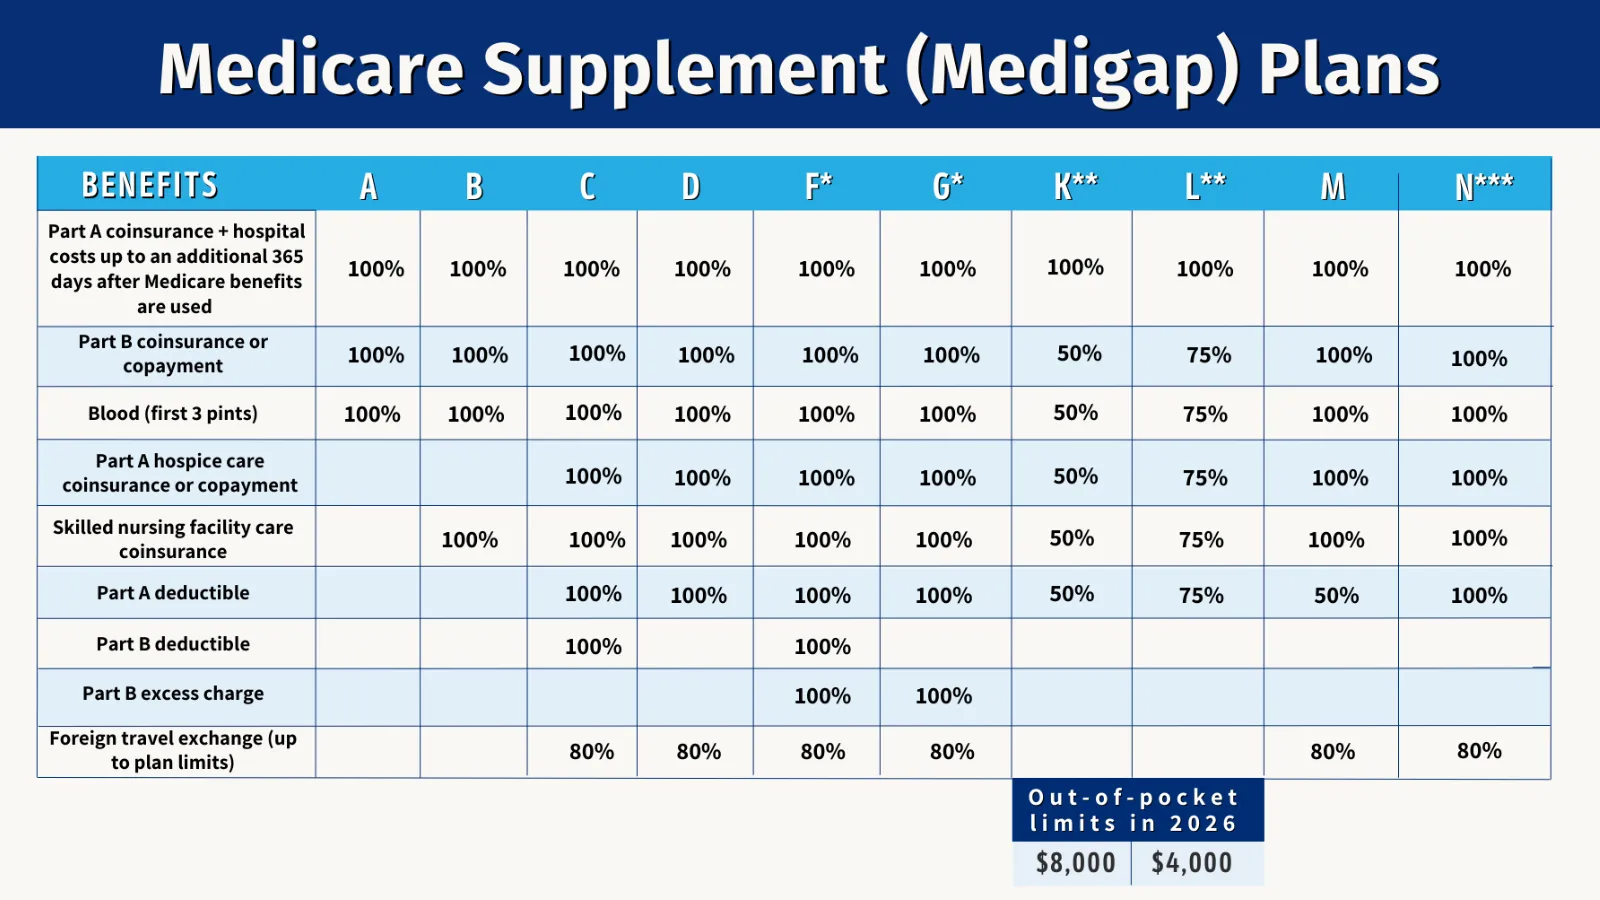
Medicare Advantage vs Medigap Coverage